Automated vs. Manual Underwriting: Getting Approved with a 580 Score
Can you get a VA loan in Las Vegas with a 580 credit score in March 2026? The answer is a definitive yes. While many "Big Box" lenders use rigid computer algorithms that auto-reject lower scores, the VA program is designed to be inclusive. When the "Automated Underwriting System" (AUS) gives a "Refer" status, Manual Underwriting allows a human being to look at your "Whole Picture" and approve your loan based on your service, stability, and future potential.
I am David Ham. Alongside my dedicated team of specialists, we specialize in the "Human Element" of mortgage lending, ensuring your 2026 homeownership goals aren't sidelined by a computer's "No."
Key Takeaways for 2026 Manual Underwriting
-
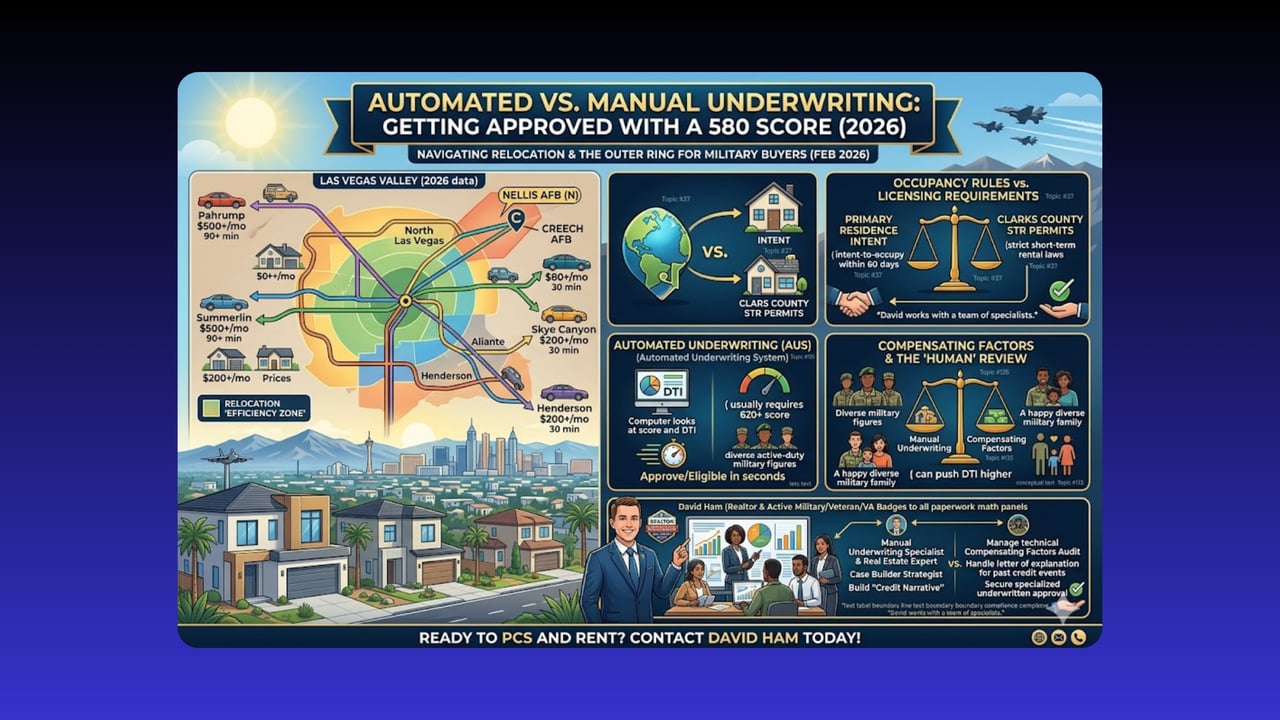
Automated Underwriting (AUS): This is the "Easy Button." The computer analyzes your score and Debt-to-Income (DTI) ratio to issue an "Approve/Eligible" status in seconds. In 2026, this usually requires a 620+ score and a relatively clean history.
-
Manual Underwriting (The Human Path): If the computer refers the file, a human underwriter takes over. They perform a deep-dive review of your 24-month payment history, your Residual Income, and your unique "Compensating Factors."
-
Leveraging Compensating Factors: To overcome a lower 2026 credit score, the VA looks for "strength" in other areas. This includes having 3+ months of cash reserves, a high BAH (Topic #2) that covers the mortgage, a significant down payment, or a long-term history of on-time rental payments in the Las Vegas valley.
-
The 41% DTI vs. Residual Income: While manual underwriting is technically stricter on debt ratios (41% DTI), the VA has a 2026 "Override." If your Residual Income is 20% above the VA's regional guideline for the West, we can often push your DTI significantly higher.
The 2026 "Human" Review
In the current Las Vegas market, many lenders have "overlays"—extra rules that reject scores below 620. My team and I work exclusively with VA-Specialized Lenders who embrace manual underwriting as a core part of their mission. We focus on your "Last 12 Months" of clean credit. The VA cares more about the stable, responsible person you are in 2026 than a credit mistake you made three years ago during a deployment or PCS move.
Your Manual Underwriting & Real Estate Team
I am your Manual Underwriting and Real Estate Expert. While my trusted team of specialists handles the technical "Case Building" for the underwriter and performs a "Compensating Factor Audit" on your assets, I focus on your "Credit Narrative."
I’ll help you draft a professional Letter of Explanation (LOE) for past credit events that highlights your 2026 income stability and your commitment to your community. I ensure the human underwriter at the Regional Loan Center sees the "Hero" behind the credit score, making the argument that your service and reliability far outweigh a three-digit number.
Worried Your Credit Score Isn't "Vegas Ready"?
Don't let a computer's "Refer" status stop you. Let’s build a case for your approval today. Contact David Ham, your Active military, veteran and VA real estate expert today, and my team and I will provide our exclusive "2026 Manual Underwriting Success Kit" to help you get the green light!